Saudi Arabia remained the GCC’s largest projects market in Q3 2026, even as the region’s overall awards fell sharply year on year. Kamco Invest’s tracking of contract awards put Saudi awards at USD 24.4 bn during the quarter, versus USD 33.2 bn a year earlier, while GCC-wide awards fell 37.2% y-o-y to USD 47.4 bn. That contrast matters for reading Saudi Arabia construction awards Q3 2026: the Kingdom still led the region by value, but it did so in a weaker awards environment where fewer markets had the fiscal and corporate “cushion” to keep signing at prior levels.
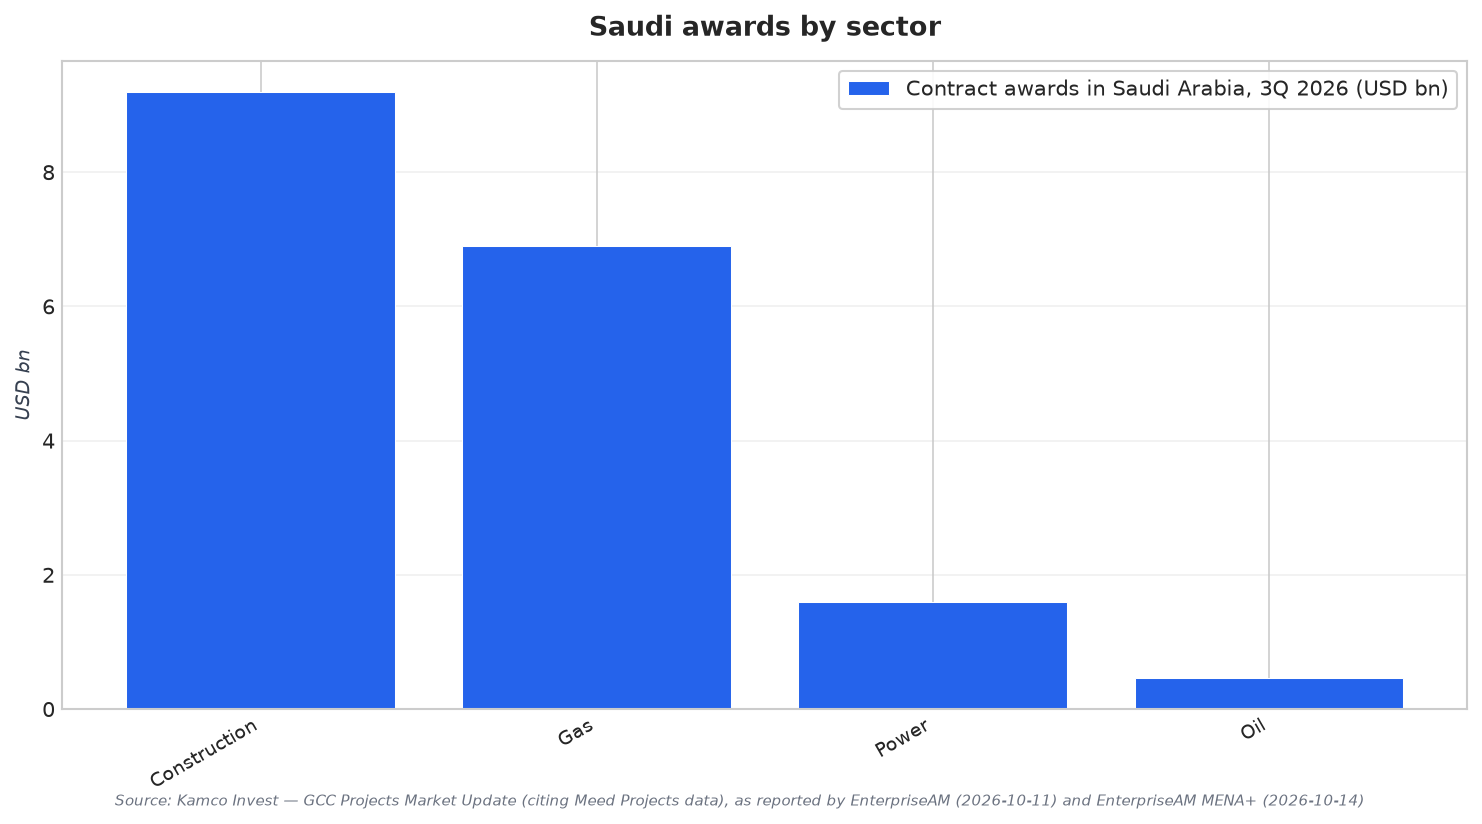
The sector mix explains where awards were still flowing in the Kingdom. In Q3, construction contracts led Saudi’s award table, rising 7.6% y-o-y to USD 9.2 bn. Gas awards also accelerated, jumping 80.1% to USD 6.9 bn. Other major segments moved the opposite way. Oil awards collapsed to USD 460 mn from USD 3.8 bn a year earlier, while power awards fell 83.4% to USD 1.6 bn. The data points to a market still committing capital, but doing so in a narrower set of segments than the year before.
Aramco’s Spending Plans and What They Signal for Awards
Aramco remained central to the awards and investment picture. The company earmarked USD 50–55 bn for investment in 2026, with roughly 65–70% directed to oil and gas, and it had already spent USD 12.3 bn on upstream contracts by the quarter, with the largest share going to development of the Dorra gas field. While Q3’s oil-award value was far lower than the prior year, these figures help explain why gas-linked work continued to show momentum, even as award volumes and some sectors’ totals came under pressure.
Two healthcare awards also stood out among Q3 contract announcements. These included USD 208 mn for mechanical, electrical, and plumbing works at Almoosa Hospital in Al-Khobar, and a USD 105.6 mn contract to finish Taiba University Hospital in Madinah, covering remaining civil works, building systems, clinical fit-outs, and medical-gas infrastructure. Alongside construction and gas totals, these examples underline that awards were still landing in non-energy social infrastructure, even during a quarter when Saudi’s overall awards value was lower than the year before.
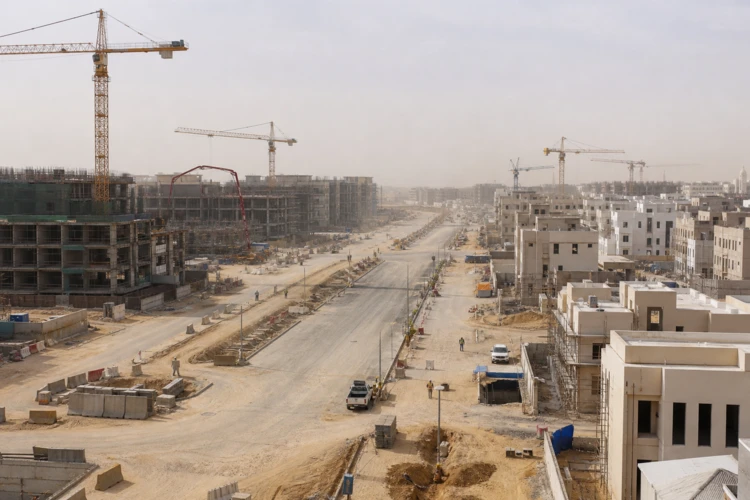
On-the-ground activity did not mirror the slowdown in new awards. The Al Rajhi Capital Saudi Construction Index reached 55.4 in August, up from 55.2 in July, marking a fifth straight month above the 50 contraction line, though it was described as the slowest pace in four. All three segments expanded, with residential at 56.6, infrastructure at 55.8 (up from 53.9), and non-residential at 50.9. Costs, however, rose quickly: around 45% of firms reported higher input prices in September and fewer than 1% reported a decline, taking input-cost inflation to its fastest since the survey began in January. Even so, 34% expected activity to rise over the next three months, versus 8% expecting a fall.
What was the value of Saudi Arabia’s project awards in Q3 2026?
Which sectors grew in Saudi Arabia during Q3 2026 awards?
How does the Saudi Arabia construction awards Q3 2026 picture compare with the wider GCC?
What did the Saudi Construction Index say about activity during the quarter?
What recent contract examples show awards still flowing beyond energy?